

Key Takeaways
- Europeans do not see cash and digital payments as competing alternatives. Survey findings suggest citizens overwhelmingly support a future in which both remain available, preserving the freedom to choose how they pay.
- Cash remains a critical component of resilience. More than 9 in 10 respondents view cash as important during power outages, cyber incidents, and other disruptions that affect digital payment systems.
- Citizens associate cash acceptance with inclusion and equal participation. Respondents expressed strong concern about the exclusion of vulnerable populations and believe access to public services should not depend on an individual's ability to use digital payment tools.
Public opinion doesn’t (and shouldn’t) dictate policy in modern democracies — policymakers must balance competing interests, evaluate complex tradeoffs, and make decisions that measure both present realities and future needs. Still, listening to citizens is one of the foundational principles of democratic governance. If governments consider policies that affect everyday life, it’s essential for them to understand what people want.
That principle is particularly relevant as European policymakers enter the final stages of negotiations on the proposed EU Legal Tender for Cash Regulation. The legislation is intended to clarify how euro cash should be accepted and made available across the European Union in the years ahead. But what if the direction of those negotiations were guided by the people who will ultimately live with the outcome? What if citizens themselves could shape the future framework governing cash acceptance and access? What would that future look like?
The answer may surprise some. Europeans clearly embrace the convenience of digital payments, with card and mobile payment use growing steadily in recent years. But support for the benefits that digital payment technologies can provide doesn’t appear to come at the expense of cash. Rather than choosing one payment method over another, most people favor a future in which both remain available, where they have the freedom to decide for themselves how they wish to pay. Asked to help define their financial future, people clearly opt for an “all of the above” approach.
That is the central finding of a new survey conducted by independent polling firm Civey on behalf of the International Security Ligue Cash Chapter. Based on responses from 5,000 citizens in Germany, the survey found overwhelming support for preserving access to and acceptance of cash. Most notably, 92 percent of respondents said they want banknotes and coins to remain accepted and readily available throughout Germany and the European Union. At a time when policymakers are debating the future role of cash in an increasingly digital economy, the findings offer a clear signal that citizens continue to view cash as an important component of the future payments landscape.
92% Want Cash to Remain Accepted and Available
The survey's headline finding is difficult to ignore: 92 percent of respondents want banknotes and coins to remain accepted and readily available throughout Germany and the European Union. Rather than suggesting resistance to digital innovation — payment trends clearly show support for card, mobile, and online payment technologies — the 92% figure says that citizens favor a future in which cash and digital payments coexist, and that their freedom to choose is preserved.
“Digital innovation and cash are not mutually exclusive. Both have an important role to play in a modern payment system,” emphasized Tanja Kulisch-Ziemens, Secretary General of the International Security Ligue Cash Chapter. “The real question is whether citizens will continue to have genuine access to the payment methods they need and trust.”
That distinction is important. Acceptance and access are often discussed as though they were the same thing, but they address different challenges. A payment method cannot be meaningfully accepted if it is no longer readily available, and it cannot remain available if the infrastructure supporting it steadily disappears. Across Europe, the number of bank branches and ATMs has been declining for years, raising concerns about the emergence of so-called "cash deserts" where access to cash services has eroded to the point of exclusion. In such communities, obtaining cash can become increasingly time-consuming, costly, or impractical, particularly for older adults, rural residents, and those with limited mobility.
Thus, the survey's results suggest people are supporting something broader than cash itself: They are signaling a desire to preserve meaningful payment choice. For cash to remain a viable option, it must not only continue to be accepted where people reasonably expect to use it, but also accessible through the infrastructure that makes that possible.
Why More than 9-in-10 People See Cash as Critical in Crisis
Another survey finding is equally striking: 92 percent of citizens say cash remains important for ensuring access to essential goods and services during power outages, internet disruptions, and other emergencies.
Discussions around cash initially focused on convenience, but resilience has lately taken up a greater share of the conversation. As payment systems become more digital, they become more dependent on a complex web of supporting infrastructure, including telecommunications networks, cloud services, payment processors, software platforms, and electricity. Normally, these systems operate fine, but when one or more components fail, there are immediate and significant disruptions to the ability to make or accept payments.
“Cash is more than just another payment method. It is an essential part of a resilient and inclusive payment system,” said Tanja Kulisch-Ziemens, Secretary General of the International Security Ligue Cash Chapter. “When electricity fails, internet connections are disrupted, or digital systems become unavailable, cash provides an important alternative. And for people who cannot or do not wish to rely exclusively on digital payments, it remains indispensable.”
Central banks and financial authorities around the world have increasingly stressed the importance of maintaining multiple, interoperable payment channels. Cash remains unique in this regard. It is the only widely accepted payment method that functions independently of digital networks and can continue to facilitate transactions even when electronic systems are unavailable.
Resilience is not measured by how systems perform during normal conditions, [but] by what happens when conditions are not normal.
Recent events have highlighted why this redundancy matters. Retailers, payment processors, telecommunications providers, and public agencies have all experienced outages in recent years that temporarily affected digital payment services. At the same time, the cyber threat landscape is becoming more complex. In 2026, both the European Systemic Risk Board and the International Monetary Fund warned that advances in artificial intelligence could accelerate cyberattacks against critical financial infrastructure, increasing the potential for disruptions that affect payment systems at scale.
This is not to say that that digital payments are unreliable — indeed, they offer daily efficiencies and convenience — but resilience is not measured by how systems perform during normal conditions. It’s measured by what happens when conditions are not normal. Viewed through that lens, the survey finding suggests that citizens understand what policymakers are waking up to: payment systems are strongest when they provide alternatives rather than dependencies.
Inclusion and Equal Participation
The survey's findings suggest that public attitudes toward cash extend beyond convenience, preference, and resilience. Respondents also appear to view cash through the lens of inclusion and equal participation in society.
A vast majority of respondents, 88%, expressed concern that older people and people with disabilities could be excluded from everyday life if only digital payments were accepted. Similarly, 82% believe the principle of equal participation is compromised when public offices, government agencies, and public transportation systems no longer accept cash.
These concerns reflect a reality that is sometimes overlooked in discussions about digitalization. While digital payment technologies offer significant benefits, not everyone experiences those benefits equally. For some people, barriers can include access to banking services, digital literacy, connectivity, physical disabilities, or the simple desire to manage finances using cash. As a result, a payment option that appears merely convenient to one person may be essential to another.
The average citizen recognizes this distinction, the survey suggests. Respondents want to preserve their own payment choices, but they also acknowledge the needs of others who may face obstacles participating in an increasingly digital economy.
Nobody would build a modern skyscraper without stairs simply because it has elevators. Nor should we design our payment system to rely exclusively on digital solutions. — Tanja Kulisch-Ziemens, Secretary General of the International Security Ligue Cash Chapter
The role of public institutions adds another dimension to the discussion. Governments provide services that citizens cannot readily obtain elsewhere, from transportation and permits to taxes, fees, and administrative services. For this reason, many respondents appear to apply a different standard to public agencies than they might to private businesses. If access to public services is intended to be universal, payment methods accepted by those services may also need to accommodate the broadest possible range of citizens.
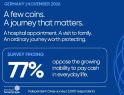
These concerns are not occurring in a vacuum. The survey found that 77% of respondents view the growing refusal of cash payments in everyday situations, including at government offices, on public transportation, and at parking facilities, negatively. That finding suggests citizens are not simply speculating about a future possibility. Many believe the shift away from cash acceptance is already occurring and are increasingly concerned about its potential effects on accessibility and participation.
This expectation is not unique to Germany. Policymakers in a growing number of countries have grappled with questions about whether the continued acceptance of cash is necessary to prevent exclusion and ensure equal access to goods and services. While approaches vary, a common concern has emerged: as payment systems evolve, the benefits of innovation should not come at the expense of accessibility.
Viewed together, the survey's 88%, 82%, and 77% findings point toward a broader public expectation. Citizens appear to support a payment landscape that is not only efficient and modern, but also inclusive. People are concerned not only with how they can pay, but also with ensuring that everyone can participate fully in economic and civic life and that essential services remain accessible regardless of payment preference.
What the Results May Mean for Policymakers
As policymakers negotiate the future framework governing euro cash, they are exposed to no shortage of perspectives. Governments, regulators, financial institutions, payment providers, retailers, consumer advocates, and industry associations all bring their own priorities to the discussion. Much less often, however, do policymakers receive such a clear signal about what ordinary citizens want from the future payments landscape. In that respect, the new survey offers a valuable contribution to ongoing discussions surrounding the EU's Legal Tender for Cash Regulation.
Citizens support a payment landscape that is not only efficient and modern, but also inclusive.
Taken together, the findings present a remarkably consistent picture. Respondents expressed strong support for preserving payment choice, maintaining access to cash, ensuring access during crises, and protecting vulnerable populations from exclusion. While each result addresses a different aspect of the issue, together they suggest that citizens view cash as serving a broader purpose than simply facilitating transactions.
“As policymakers shape the future of payments in Europe, they should take these public expectations seriously,” Kulisch-Ziemens concluded. “Innovation, efficiency, and digitalization are important. But they must not come at the expense of inclusion, resilience, or the freedom to choose how we pay.”
The results also challenge the notion that the debate is one of cash versus digital payments. Rather than rejecting digital innovation, respondents appear to favor a payment ecosystem in which multiple options remain available, allowing individuals to choose the methods that best meet their needs.
For policymakers participating in the trilogue negotiations, that distinction may be significant. The survey suggests that citizens' primary concern is not preserving cash for its own sake, but preserving the choice, resilience, accessibility, and inclusion that cash helps provide. People want digital innovation to continue, but not at the expense of resilience, inclusion, or the freedom to choose how they pay.
So, what would Europe's payments landscape look like if citizens had a direct hand in shaping it? According to the survey, it would not be a choice between cash and digital payments. It would be a system that embraces both, preserving innovation while maintaining the choice, resilience, accessibility, and inclusion that cash continues to provide.